 TIMBERVIEW CAPITAL
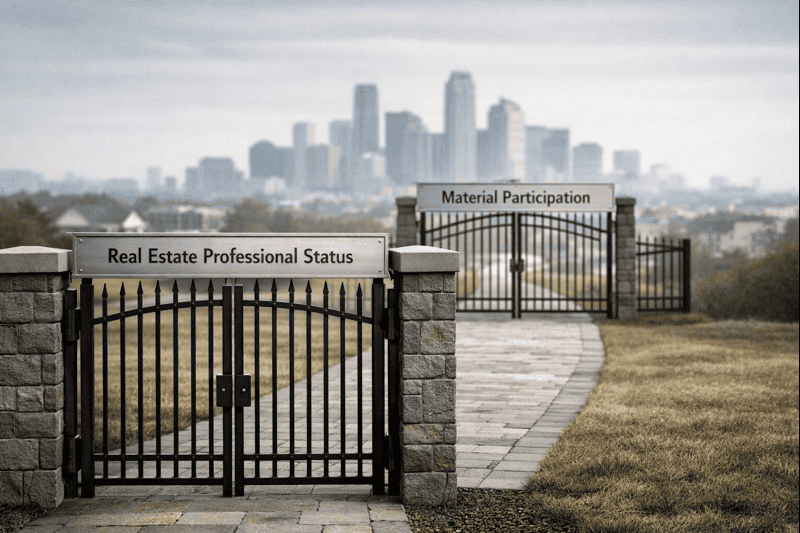
For real estate investors with high incomes, one tax designation comes up again and again: Real Estate Professional Status (REPS). This guide covers what the status is, how investors qualify, and the tax benefits it can unlock as part of a broader tax strategy.
We’ll walk through the qualification criteria, the deductions and benefits REPS can change, what it doesn’t change, and a few simple examples. For the IRS rules and hour tests in full detail, see our companion guide, Real Estate Professional Status: What It Is and Common Myths.
- REPS can let rental losses, including depreciation, offset other income, such as wages.
- You must meet both time tests every year and materially participate in your rentals.
- REPS doesn’t automatically remove the NIIT or change how a sale is taxed.
Understanding real estate professional status
Real Estate Professional Status is recognized by the IRS under Internal Revenue Code Section 469(c)(7). It allows individuals actively involved in real estate activities to treat rental real estate as non-passive, offering a pathway to offset rental losses against other forms of income.
Without the status, rental real estate is generally passive, and passive losses usually offset only passive income.
Criteria for qualification
To qualify for REPS in a tax year, investors must meet specific IRS criteria:
- Time commitment. Devoting more than 50% of working hours during the tax year to real property trades or businesses in which you materially participate, and performing more than 750 hours of services in those real property trades or businesses during the year. Both tests must be met.
- Material participation. Actively participating in the management and decision-making of each rental activity. REPS removes the automatic passive label, and material participation is what makes a rental loss nonpassive.
On a joint return, one spouse has to meet both time tests separately. Hours can’t be combined for the tests, though a spouse’s participation does count toward material participation (IRS Publication 925).
REPS tax benefits: what the status can change
When both gates are cleared, here are the benefits and how they can reshape your tax strategy.
Rental activity becomes nonpassive
Your rental activity is no longer passive by default. Rental income and expenses are reported as nonpassive, which is what opens the door to the other benefits below.
Rental losses can offset other income
If a rental property shows a loss, a qualifying real estate professional can offset that loss against other income, such as wages or business income, reducing the overall tax bill. Other limits, such as basis, at-risk, and excess business loss rules, still apply.
Accelerated depreciation becomes usable
With accelerated depreciation, you deduct a substantial portion of a rental property’s cost in the early years of ownership. With REPS, those deductions can reduce taxable income from other sources. See cost segregation studies: what they are and when they matter.
A possible path around the 3.8% NIIT
Rental income escapes the 3.8% Net Investment Income Tax (NIIT) only when it is earned in the ordinary course of a trade or business. Treasury regulations include a safe harbor for real estate professionals who meet additional participation requirements (Treas. Reg. 1.1411-4).
What REPS doesn’t change
- The NIIT is not automatic. Qualifying for REPS does not by itself exempt rental income from the NIIT. The trade-or-business standard and the safe harbor above are separate questions for your CPA.
- How a sale is taxed. REPS isn’t a way to turn a gain into a different, lower-taxed kind of income. How gains and depreciation recapture are taxed on a sale is a separate question for your CPA.
Examples: how REPS plays out for investors
Here are a few simple examples of how the status can work in practice.
Susan
Susan qualifies as a real estate professional and materially participates in her rentals. Her rental activity is no longer a passive player. Her rental income and expenses are treated as nonpassive, which changes how her real estate fits into her overall tax picture.
James
James is another real estate professional. His rental property took a $20,000 hit due to unforeseen circumstances. Because he qualifies and materially participates, he can offset this loss against his other income, reducing his overall tax bill.
Sarah
Sarah is a real estate professional using accelerated depreciation. She deducts a substantial chunk of her rental property’s cost early on, creating significant savings in taxable income.
John
John is a real estate professional whose rental activity rises to the level of a trade or business. He works with his CPA to see whether his rental income can fall outside the 3.8% Net Investment Income Tax (NIIT) under the real estate professional safe harbor.
Alex
Alex is a real estate professional selling a rental property. He learns that REPS doesn’t change how his profit is taxed, so he plans the sale with his CPA ahead of time, including options like a 1031 exchange.
Record-keeping tips
Meticulous record-keeping is your playbook. Keep detailed logs of your time spent on real estate activities, documenting your involvement throughout the year. Pub 925 allows any reasonable method of proof, such as an appointment book, calendar, or narrative summary, but records kept during the year, backed by emails, invoices, and calendar entries, are far more persuasive than a log rebuilt at tax time. This evidence is your key to unlocking the benefits of REPS.
Challenges and considerations
Meeting the criteria for real estate professional status requires careful planning. For most practicing physicians, the time tests are hard to meet personally, because real estate hours would have to exceed hours in medicine. Investors with diverse portfolios should assess the impact on their overall tax strategy and make informed decisions.
Staying informed: changes in tax laws
Just like the real estate market, tax laws can shift. Stay informed about updates that may affect REPS and consult with tax professionals to adapt your strategies accordingly.
Exploring alternatives and additional strategies
Real Estate Professional Status might not be the best fit for everyone. Explore alternative tax strategies and other ways to optimize your tax position within real estate, such as cost segregation, 1031 exchanges, and discounted Roth conversions. Your tax strategy should be as unique as your real estate portfolio.
The bottom line
Real Estate Professional Status is more than a title. It is a strategic move in your tax plan. By understanding the criteria, benefits, and limits of this designation, investors can strengthen their financial strategies and reduce their tax liability along the way. Consult with tax professionals to make sure your plan is tailored to your circumstances.
Sources: IRC Section 469; IRS Publication 925; Treas. Reg. 1.1411-4.
Build a tax-aware real estate plan
Want to see how passive real estate investing fits your tax strategy? Schedule a call with Timberview Capital.