 TIMBERVIEW CAPITAL
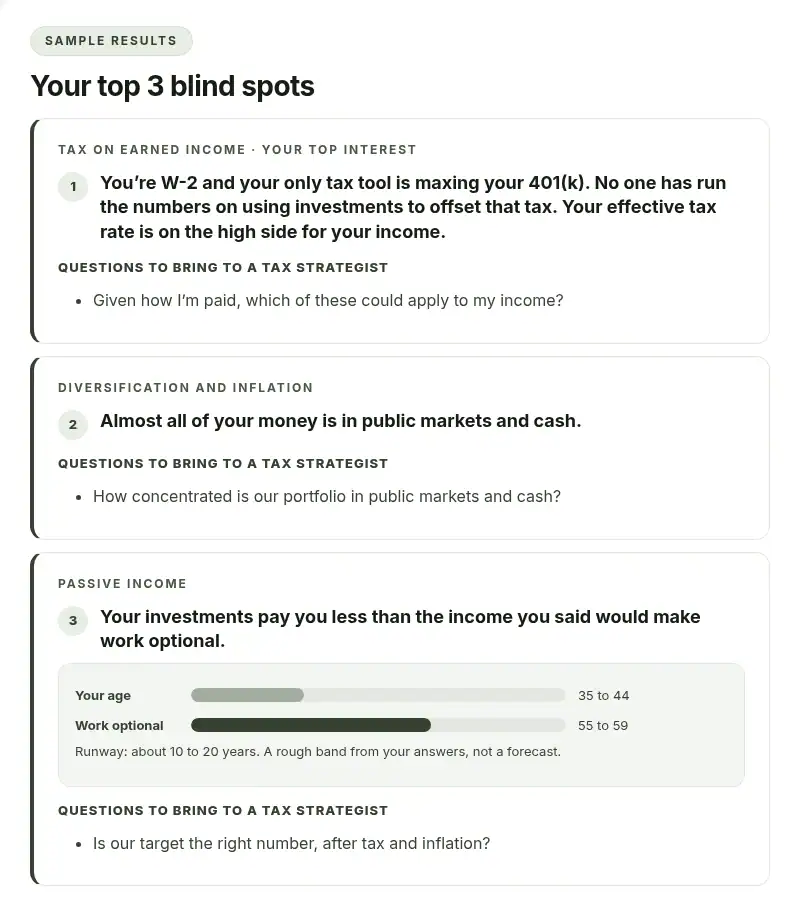
Many high earners reach mid-career with a strong income, disciplined savings, and a quiet worry: will it be enough to keep the life they have built? That worry has a name.
The Retirement Paradox is the challenge high earners face when trying to sustain their pre-retirement lifestyle despite years of financial success. Many assume that a high income and disciplined savings will be enough. But traditional retirement strategies often fall short because of capped savings options, tax inefficiencies, increased longevity, and inflation.
- People are living longer, so retirement savings have to last longer.
- Social Security and capped retirement accounts replace a smaller share of a high earner’s income.
- Real estate can add cash flow, inflation protection, tax efficiency, and diversification to a retirement plan.
Why retirement is harder to fund than it used to be
In recent decades, the global population has gone through a major demographic shift. Historically, less than 2% of the world’s population lived to age 65. Today, people aged 65 and older make up approximately 10% of the global population.
In 2020, the number of people aged 60 years and older outnumbered children younger than 5 years. The trend is projected to continue: the share of the global population over 60 is expected to nearly double, from 12% in 2015 to 22% by 2050 (WHO, 2024).
As longevity increases, so does the financial challenge of maintaining your standard of living after retirement. That is especially true for high-income earners who have grown used to a certain lifestyle.
The result: many people find themselves financially unprepared for retirement despite years of earning a high income. Longer lifespans require more money, and traditional retirement strategies often fail to provide the sustained income needed to keep the same standard of living.
The retirement income gap for high earners
Conventional retirement planning suggests replacing 70% to 90% of pre-retirement income to sustain a similar standard of living. For high earners, hitting that target is harder than it looks. Here’s why.
Limited Social Security benefits
Social Security is designed to replace a smaller percentage of income for high earners. In 2024, individuals with maximum taxable earnings of $168,600 could expect Social Security to replace just 28% of their pre-retirement income (Yahoo Finance).
Savings constraints
Contribution limits on tax-advantaged retirement accounts, such as 401(k)s and IRAs, cap how much high earners can save efficiently. In 2024, the maximum 401(k) contribution limit was $23,000, with an additional $7,500 catch-up contribution for those over 50. These accounts help, but they may not be enough to sustain a high-income lifestyle in retirement.
Longevity risk
With people living longer, retirees must make sure their savings last 25-30 years or more.
Early or forced retirement
Many people are unable to retire at 65 or 67 because of financial limits. Others are forced into retirement by health concerns, caregiving responsibilities, or other factors beyond their control (Sage Journals, 2023). Many high earners also find that traditional retirement investments, such as stocks and bonds, may not provide enough long-term financial security. All of this points to the need for a passive income strategy.
Real estate as a solution to the income gap
Traditional retirement savings vehicles often fail to generate enough income to sustain a high-earning lifestyle after retirement. Stock market volatility, limited tax-advantaged savings options, and the risk of outliving your savings make alternative strategies essential. For high earners looking for a reliable way to bridge the retirement income gap, real estate investing offers several compelling advantages.
Predictable cash flow
Unlike stocks, which are subject to market volatility, well-placed real estate investments can generate steady rental income, giving retirees a dependable passive income stream. Multifamily properties, triple-net lease commercial buildings, and short-term rental investments offer opportunities for predictable returns.
Protection against inflation
Real estate values and rental income generally rise with inflation, preserving purchasing power in a way that fixed-income investments, like bonds, do not. With inflation remaining a significant concern, real estate serves as a valuable hedge against eroding wealth (Forbes, 2022). More on this in how inflation destroys idle cash.
Tax efficiency
Real estate offers several tax advantages:
- Depreciation deductions that reduce taxable income.
- 1031 exchanges to defer capital gains taxes by reinvesting in like-kind properties.
- Cost segregation strategies to accelerate depreciation and maximize tax benefits.
Diversification beyond stocks and bonds
Relying only on stocks and bonds exposes retirees to market downturns, which can be devastating once you are drawing down savings. Real estate is a tangible, cash-flowing asset that can diversify a retirement portfolio and reduce reliance on stock market swings. Compare the two in multifamily vs. the stock market for a physician’s retirement.
Passive investing opportunities
Many high earners lack the time or interest to manage properties themselves. Real estate syndications let investors participate in high-quality deals without the burden of day-to-day management. Investors can enjoy hands-free passive income while benefiting from the expertise of seasoned real estate professionals. See why multifamily syndications suit busy physicians.
High equity multiple investment opportunities
Some of our real estate investment opportunities create high equity multiples, meaning they aim to double investor capital over the shortest period of time possible. Doubling with each cycle can create exponential wealth growth.

How to build a real estate strategy for retirement
If you are considering real estate as part of your retirement plan, here are the key steps.
1. Assess your financial goals
Work out how much passive income you need to replace your earnings and maintain your lifestyle.
2. Select the right investment model
Choose between direct ownership, syndications, or real estate funds based on your risk tolerance and how involved you want to be.
3. Use the tax strategies available to you
Work with a tax professional to maximize real estate’s tax benefits and structure investments efficiently. High equity multiple funds that are tax advantaged create exponential wealth growth, partly by optimizing tax mitigation.
4. Partner with experts
Join forces with experienced real estate investment firms to access high-quality, professionally managed opportunities.
The bottom line on the retirement paradox
The Retirement Paradox, where high earners struggle to replace their income despite years of financial success, exists because traditional retirement strategies are not sufficient for most high-earning professionals.
Building wealth is easier with a high salary. Sustaining the same lifestyle in retirement is harder, because of limits on tax-advantaged savings, capped Social Security benefits, and the unpredictability of market-based investments. This is a reality to address early, not on the eve of retirement.
With longer lifespans, rising inflation, and constrained traditional savings options, a well-structured real estate investment strategy can provide the reliable passive income you need to maintain financial security. For a fuller plan, see our guide to retiring early with real estate or the Wealth by Design book.
Secure your retirement with real estate
Timberview Capital can help. Schedule a call today and learn how you can invest alongside experienced professionals to build a stable, income-generating portfolio for the future.