 TIMBERVIEW CAPITAL

Cash feels safe. But holding too much cash is costly.
Inflation works quietly. It takes a little every day. Most of us never notice the loss, because the number in the bank account does not change. The real buying power does.
If you want to grow wealth, protect what you have, and stay ahead of rising costs, it helps to understand exactly what inflation does to idle cash.
- Inflation shrinks what your cash can buy, even when the balance never moves.
- Idle cash earns less than inflation, does not compound, and delays wealth building.
- Keep cash for the jobs only cash can do. Money with no job may work harder in real assets.
How inflation eats idle cash
Inflation means the cost of goods and services goes up over time. The United States has averaged about 3% inflation per year over the long term, according to the Bureau of Labor Statistics. In high-inflation years like 2021 and 2022, the rate climbed above 7%.
Here is what that looks like in practice:
- You hold $100,000 in a bank account that pays almost nothing.
- Inflation is 4%.
- Your money loses $4,000 of buying power that year.
The number stays the same. What you can buy with it gets smaller. Food, housing, equipment, labor, and services all go up. Your cash stays flat.
This is why economists at the Federal Reserve often describe cash as a melting ice cube. It slowly shrinks, even when it looks solid. For instance, $100 in 1990 has been estimated to have the same buying power as approximately $248 in late 2024 or early 2025.
Nominal vs. real: the number that matters
Economists separate two ideas that are worth keeping straight:
- Nominal is the number on your statement.
- Real is what that number can buy after inflation.
A checking account is very good at protecting the nominal number. It is much less good at protecting the real one. That gap is the cost of waiting, and it is easy to miss because nothing on the statement ever goes down.
Why idle cash costs investors
Investors do not lose money only when the market goes down. They also lose money when their cash does nothing while prices rise. Idle cash has three problems.
It earns less than inflation
Most savings accounts pay under 1%. Inflation is often 3% to 4% or more. That means the real return is negative.
It does not compound
Money grows when it works. Cash sitting in a low-yield account does not grow or compound.
It delays wealth building
Every year you wait to invest is a year of lost compounding. Over the decades, that adds up to a huge difference.
Why high-income physicians are hurt most
High earners often keep large sums of cash in reserve. It feels responsible. But the cost is silent.
Many of us in medicine tell the same story:
- We earn a strong income.
- We save more than average.
- We keep the extra in cash until things calm down.
- Years pass.
- Inflation erodes the value.
- Opportunities are missed.
This pattern slows wealth growth. It also delays retirement and adds stress about the future.
Why investors keep cash even when it loses value
It is not because they are wrong. It is because they want:
- Safety
- Liquidity
- Confidence
- A plan they understand
But cash is not the only place to find these things.
Well-built real estate deals offer predictable income, long-term value, tax benefits, and stability backed by real demand. Medical offices, multifamily housing, and other real assets grow value when inflation rises. If you want to go deeper on property types, start with why medical real estate and multifamily syndications for busy physicians.
What happens when capital works instead of sits
When capital is deployed into real assets, it can do four things.
Grow faster than inflation
Real estate values and rent both rise with inflation. This helps keep pace with rising costs.
Produce cash flow
Instead of losing 3% to 5% a year to inflation, investors may earn steady income from rent or distributions.
Reduce taxes
Many real estate investments offer depreciation and bonus depreciation that offset income and protect returns. See our guide to cost segregation studies.
Compound over time
When income is reinvested, wealth grows at a much faster pace.
This is why private real estate and private equity have outperformed public markets over the past 35 years, as large financial studies have shown. Dr. Cobb shares how redeploying capital and investing in strong deals helped him accelerate his net worth far faster than holding cash or traditional assets alone. He explains his process in his book, Wealth by Design.
A simple example: two investors, $100,000 each
Imagine two investors who each start with $100,000.
Holds cash
Inflation is 4%. After one year, the buying power is $96,000. After five years, the buying power is about $80,000.
Invests in real estate with a 7% return
At the end of five years, the investment grows to about $135,000. The investor also receives tax benefits and equity growth.
Now add the tax and equity side for Investor B. Say you receive $70,000 in depreciation and your combined tax rate is 50%. Your tax savings would be $35,000. If the asset value appreciates at 4% annually, you would also pick up another $20,000 in asset value. That brings the total return to $90,000. Added to the original $100,000 investment, the total value would be $190,000.
Same starting point. Very different outcomes. The difference is not timing the market. It is simply putting money to work.
How much cash should you keep?
Experts often suggest keeping enough cash for three jobs. A simple way to think about it is three buckets:
- Now: emergencies. A job change, a disability waiting period, a family emergency, or a large unexpected bill.
- Soon: short-term needs. Bills and obligations coming up in the near term, such as a large tax payment.
- Planned purchases. A down payment, tuition, or a practice buy-in you already know is coming.
Anything beyond that may work better when invested in assets that fight inflation.
This does not mean rushing. It means making informed choices: choosing investments with real income, real assets, real tenants, and real demand. That is the same approach Timberview Capital uses when vetting medical office, multifamily, and other commercial opportunities.
Questions to bring to your advisor
- How many months of expenses should my emergency fund cover, given my job and my insurance?
- What known expenses do I have coming up, and is that money held somewhere appropriate?
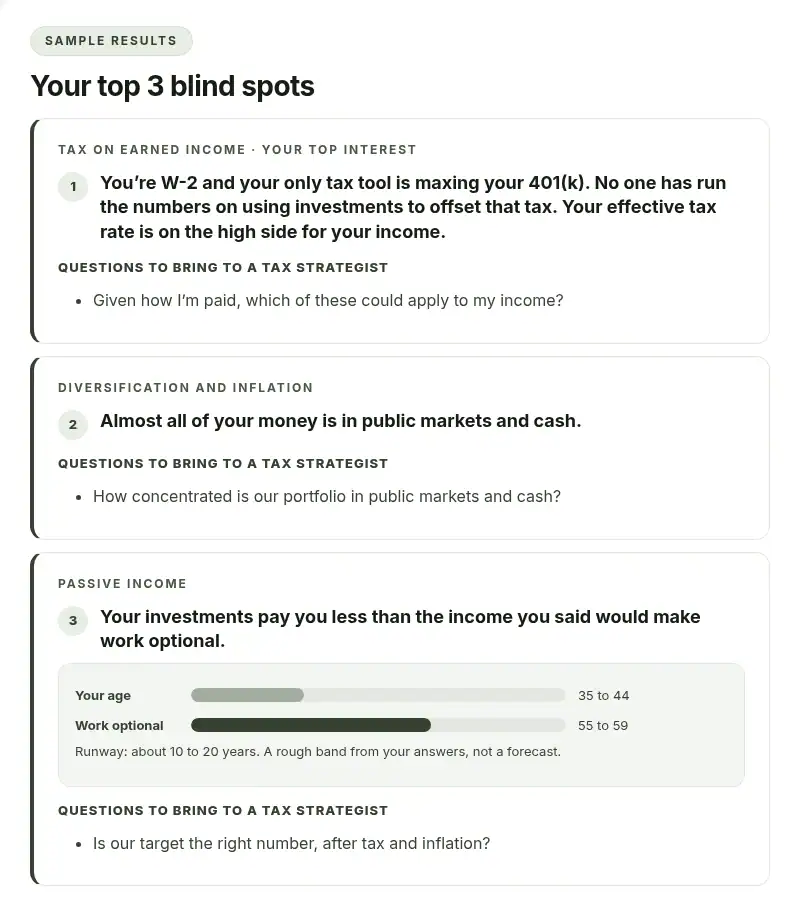
- How much of my cash has no job right now?
- What am I actually earning on my cash today, after taxes?
- Are there tax-advantaged accounts I am not using?
Asking these on purpose is the shift from earning well to building wealth. Dr. Cobb writes about that shift in High Income vs. True Wealth: A Surgeon’s Perspective.
Frequently asked questions
Does inflation really hurt money sitting in the bank?
Yes. If your cash earns less than the rate of inflation, its buying power shrinks every year, even though the balance stays the same.
How much cash should I keep?
Enough for emergencies, short-term needs, and planned purchases. Anything beyond that may work better when invested in assets that fight inflation.
Is holding cash a mistake?
No. Cash has important jobs. The cost comes from holding far more than those jobs need, for years at a time.
Why do real assets help against inflation?
Real estate values and rent both rise with inflation, which helps keep pace with rising costs. Well-built deals can also add income and tax benefits that idle cash cannot.
The bottom line
Inflation is quiet but powerful. Doing nothing is not neutral. It is costly.
Idle cash shrinks buying power, delays wealth building, and holds investors back from financial freedom. Putting capital to work in real assets can help protect money, grow it faster, and create steady income for years to come.
You do not need to take big risks. You just need to avoid the biggest risk of all: letting your money sit still while the world gets more expensive.
Put idle cash to work, on purpose
If you want help exploring income-producing investments backed by real assets and real demand, our team is here to guide you.