 TIMBERVIEW CAPITAL
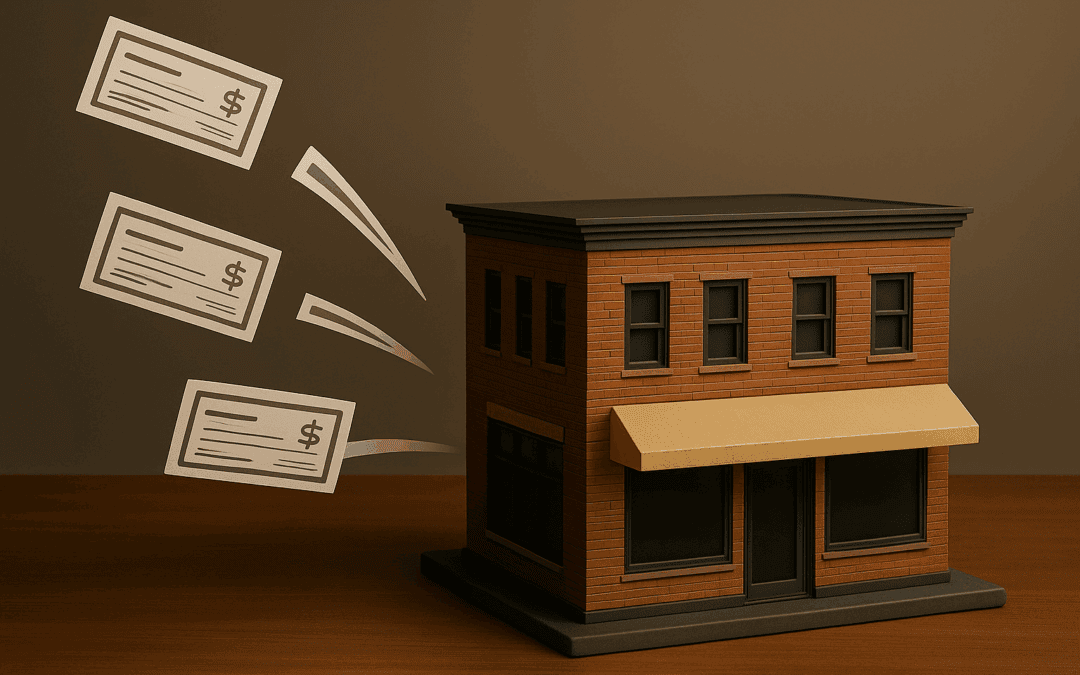
Cash flow drives the economy, and nowhere is this more evident than in small businesses. Even profitable companies experience delays waiting for customers to pay invoices, seasonal swings, or project-driven cash gaps. Instead of relying on slow, collateral-heavy bank financing, many turn to a modern alternative: selling a portion of their future receivables.
For investors, this creates an opportunity to earn steady, short-term yield supported by real, verified business revenue. The structure is simple: capital goes out, daily or weekly repayments begin almost immediately, and funds recycle rapidly into new deals.
In other words, investors earn income from the natural heartbeat of Main Street economic activity.
- Receivables funding is the sale of future revenue, not a loan.
- Underwriting is based on verified deposits and actual operating performance.
- Repayments start right away, so capital turns over quickly.
- The real risks are business failure, fraud, concentration and the economic cycle.
What short-term receivables are
Accounts receivable are the money customers owe a business for work already done or goods already delivered. They are short-term by nature: most invoices are due within weeks or months. When a business needs cash before those invoices are paid, it can borrow against them or sell them.
Selling accounts receivable to obtain short-term funds takes a few common forms:
Invoice factoring
The business sells specific unpaid invoices at a discount and gets cash now.
Asset-based lending
A lender advances money secured by the receivables, and the business repays it as a loan.
Future receivables purchase
The business sells a slice of its upcoming sales and repays through automated transfers. This is the structure described below.
Where investors sit
Investors supply the capital, usually through a fund that buys receivables from many businesses.
How the structure works for investors
Receivables funding operates as a self-liquidating advance secured by future revenue. The investor provides capital upfront. The business repays a fixed amount through automated daily or weekly transfers tied directly to its cash flow.
What makes this unique:
- Funding decisions are based on real cash flow and verified deposits
- Underwriting relies on actual operating performance, not projections
- Repayments begin immediately after funding
- Capital fully cycles every 4 to 12 months
For investors, this means:
Faster capital turnover → more frequent redeployment → more consistent yield opportunity.
Selling future receivables instead of borrowing
Accounts Receivable funding is not a loan, it is the sale of future revenue.
The business sells the rights to a small portion of its upcoming receivables at a discount. Repayment adjusts with actual sales, providing flexibility if revenue fluctuates.
Investors benefit because repayment starts immediately, which reduces time at risk and creates a consistent flow of capital that can be reinvested into new opportunities.
Why businesses choose AR funding
Even strong companies can face tight cash cycles. AR funding helps bridge short-term gaps and support operations such as:
Speed
Access to funds in days, not weeks.
Flexibility
Use for payroll, inventory, or project costs.
Predictability
Automated daily or weekly repayments.
Accessibility
Approval based on real revenue, not just credit score.
Scalability
As sales grow, funding capacity grows too.
Many studies link poor cash flow management to the majority of small business failures. AR funding directly tackles this challenge by providing liquidity when it is needed most.
How underwriting protects investors
Each deal begins with one key question: Can this business support frequent repayment from its current cash flow?
Underwriters review:
- Verified deposits and cash flow consistency
- Average daily balances and recent revenue trends
- Business tenure and management background
- Industry type and geographic risk
- Purpose of funds and repayment source
Well-designed underwriting relies on real, verifiable data rather than projections. Funds typically diversify across many businesses and industries, ensuring no single deal dominates the portfolio.
Historical defaults were cited between 4.5 and 6 percent, and the model was built to withstand up to 25 percent in losses before investor returns would be affected.
What investors should know
For investors, small business receivables funding combines steady yield, liquidity, and diversification.
Key advantages include:
- Monthly cash flow backed by real business activity
- Short durations, often under one year
- Strong alignment since operators earn only after investors are paid
- Diversification across hundreds of businesses
- Over half of our businesses are repeat customers
Income is typically taxed as ordinary income, but many investors view it as a reliable income stream within a balanced portfolio.
Due diligence: what to ask about
Good underwriting starts with good questions. These are the areas worth asking any receivables fund about:
- Business failure: if a business closes, the remaining receivables may never be collected.
- Fraud and misreported revenue: underwriting is only as good as the data behind it.
- Stacking: a business that takes advances from several funders at once is harder to repay.
- Concentration: too much exposure to one industry or region can hurt in a downturn.
- Economic cycle: a recession can slow sales across many businesses at the same time.
- Legal and regulatory: rules for these products differ by state and continue to change.
- Taxes: ordinary income treatment matters for high earners, so ask your CPA how it fits your situation.
Example from the field
Imagine an HVAC company earning $4 million a year. During summer, demand spikes, but the business must buy materials and pay workers upfront.
By selling $110,000 of its future receivables, it receives immediate working capital. Each day, small automated repayments are pulled from sales until the balance is fully paid over nine months.
The company completes projects faster, boosts revenue, and avoids waiting for clients to pay invoices, while investors receive consistent monthly distributions backed by repayments from many similar businesses.
This model provides short-duration exposure, predictable cash flow, and rapid capital recycling, allowing funds to be redeployed multiple times a year into a diversified pool of businesses.
Frequently asked questions
Is selling receivables the same as a loan?
No. Receivables funding is the sale of future revenue. The business sells part of its upcoming receivables at a discount, and repayment adjusts with actual sales.
Why would a profitable business sell its receivables?
To bridge cash gaps from slow-paying customers, seasonal swings, or projects that need payroll and materials upfront.
How is receivables income taxed?
It is typically taxed as ordinary income. Ask your CPA how that fits with the rest of your income.
What should I ask before investing?
How deals are underwritten, how many businesses and industries the fund holds, how defaults are handled and reported, and how and when you can get your capital back.
The bottom line
Small Business Accounts Receivable funding is a modern solution to a timeless problem, cash flow delays. It gives businesses access to money they have already earned and provides investors a short-term income strategy tied to real economic activity.
By combining strong underwriting, quick capital turnover, and clear alignment between businesses and investors, this model creates a true win-win.
In a market filled with long holds and uncertain exits, steady cash flow from everyday small businesses offers both stability and opportunity. For the bigger picture on risk, see passive income vs. passive risk.
Review the current offering
If you want to review our current Small Business Receivables investment, view the offering details here, or talk it through with our team.